Key Takeaways
- Most generic EBITDA guidance leaves owners with optimistic numbers that often fail quality-of-earnings review and trigger re-trades.
- Building a defensible adjustment schedule uses five disciplined steps: start with reported EBITDA reconciled to tax returns, normalize owner compensation, add back only excess discretionary and family-payroll items, normalize related-party rent in both directions, and isolate true one-time expenses.
- The gap between seller-adjusted and buyer-adjusted EBITDA can be where price is won or lost, because every rejected add-back is multiplied by the deal multiple.
- Commonly rejected add-backs include family members who perform necessary work, recurring marketing spend, and one-time expenses that appear in multiple years.
- McLerran & Associates builds a CPA-led, diligence-grade EBITDA analysis up front so the number has support when a buyer’s QoE team reviews it.
Schedule a Discovery Call with McLerran & Associates
Key Terms for Dental EBITDA Adjustments
This guide uses several valuation terms that matter for dental practice owners.
- Reported EBITDA: Earnings before interest, taxes, depreciation, and amortization, taken directly from the practice’s profit and loss statement, before any normalization.
- Adjusted (normalized) EBITDA: Reported EBITDA restated to reflect what a new owner would likely earn, after removing owner-specific costs and correcting non-arm’s-length arrangements.
- Add-back: An expense removed from the P&L because it will not continue under new ownership, which increases the earnings figure.
- Deduction: An adjustment that reduces the earnings figure, usually because the practice’s reported costs understate what a buyer will actually incur.
- Trailing twelve months (TTM): The most recent 12-month period of financial results, reconciled to tax returns.
- Quality of earnings (QoE): A financial review commissioned by a buyer to test whether reported earnings are real, recurring, and transferable.
- SDE (seller’s discretionary earnings): An earnings figure that adds back the owner’s full compensation, suited to a buyer who will personally work in the practice.
The adjustment schedule can differ by transaction path. Doctor-to-doctor deals are typically priced as a percentage of revenue or a multiple of net cash flow, while DSO and private equity deals are priced on a multiple of adjusted EBITDA. Specialty and practice size can also change which adjustments matter most. For a deeper look at valuation methods and multiple theory, see Dental Practice Valuation Methods: Know Your Worth and How Are Dental Practice Valuation Multiples Calculated?
How To Calculate Adjusted EBITDA for a Dental Practice
A defensible adjusted EBITDA calculation follows five connected steps.
- Start with reported EBITDA from TTM financials, reconciled to tax returns. The starting point should tie directly to filed returns, because buyers usually check this.
- Normalize owner compensation. Add back the owner’s recorded compensation, then subtract the market cost of replacing the owner’s clinical and management work. The adjustment can move in either direction, depending on whether the owner was paid above or below market.
- Add back discretionary, personal, and family-payroll items, using only the personal or excess portion. A family member who performs necessary work remains as an expense. Only above-market or unsupported compensation qualifies as an add-back.
- Normalize related-party rent in both directions. Below-market rent paid to an owner-controlled entity becomes a deduction, because the buyer will sign a market-rate lease. Above-market rent creates an add-back for the excess over market. Direction matters, and misclassifying this line can be costly.
- Separate non-recurring from recurring-but-necessary expenses. A one-time equipment write-off may qualify as an add-back. A repair that appears three years in a row usually remains as an operating cost.
The formula is: Adjusted EBITDA = Reported EBITDA + Legitimate Add-Backs − Deductions. Deductions include a market-rate replacement cost for the owner’s clinical and management work.
The table below maps each major adjustment category to its typical line items, direction, and required support documentation.
| Category | Typical Line Items | Direction | Support Required |
|---|---|---|---|
| Owner compensation | W-2 salary, draws, retirement contributions, health insurance | Add back recorded pay, then deduct market replacement cost (clinical and management, typically a percentage of owner production for a general dentist, per industry benchmarks) | Payroll records, production reports by provider, state or specialty compensation benchmark |
| Discretionary and personal expenses | Personal vehicle, club memberships, personal travel booked as CE | Add-back of the personal portion only | Invoices, credit card statements, mileage logs; buyers may request 36 months of statements |
| Family payroll | Spouse or family member W-2 compensation | Add-back of excess portion only, which is the spread between what is paid and what the role commands at market | Job description, payroll register, market compensation reference |
| Related-party rent | Rent paid to owner-controlled real estate entity | Below-market rent creates a deduction because the buyer will pay market rate. Above-market rent creates an add-back for the excess over market. | Lease agreement, independent fair-market-rent appraisal or opinion |
| One-time and non-recurring expenses | One-time equipment write-off, isolated legal settlement, COVID-era PPE purchases | Add-back, but only if the item does not appear in multiple years | Invoice, engagement letter, or payment record, isolated across three years of history |
| Recurring expenses buyers will reject | Routine marketing, recurring repairs, normal employee bonuses, understaffing savings | No adjustment, because these remain expenses | N/A, since buyers treat these as ongoing operating costs |
The following illustrative example shows how dollar amounts can move through these lines and arrive at a seller-adjusted EBITDA figure.
- Reported EBITDA: $1,200,000 from TTM financials
- Owner compensation add-back: + $350,000 of recorded owner pay
- Market replacement cost deduction: − $220,000 for a benchmarked replacement dentist and manager
- Personal vehicle and travel: + $18,000 for the personal portion
- Family payroll excess: + $12,000 above market for a family member role
- Related-party rent: − $30,000 to bring below-market rent up to market
- One-time equipment write-off: + $40,000 isolated to a single year
- Seller-adjusted EBITDA: $1,370,000 after all add-backs and deductions
The Adjustment Schedule and the Seller–Buyer EBITDA Gap
The adjustment formula only holds up when every line behind it is documented, which is what the adjustment schedule provides. The adjustment schedule is the artifact that can determine price. The table below shows how a single line can carry both an add-back and a deduction, and how the buyer-approved column can become the swing factor between seller and buyer EBITDA.
| Account | Reported Amount | Proposed Add-Back | Proposed Deduction | Net Adjustment | Supporting Document | Buyer-Approved (Y/N) |
|---|---|---|---|---|---|---|
| Owner compensation (add-back) | Recorded owner pay | Recorded owner pay | — | + Recorded owner pay | Payroll records, W-2 | Y |
| Market replacement cost | — | — | Market replacement cost | − Market replacement cost | Production report, benchmark | Y |
| Personal vehicle/travel | Personal portion | Personal portion | — | + Personal portion | Invoices, mileage log | Y |
| Family payroll excess | Recorded family pay | Excess over market | — | + Excess over market | Job description, market comp data | Y |
| Related-party rent | Recorded rent | — | Below-market shortfall | − Below-market shortfall | Lease, rent appraisal | Y |
| One-time equipment write-off | Write-off amount | Write-off amount | — | + Write-off amount | Invoice (isolated to one year) | Y |
| Recurring marketing | Recurring spend | Claimed | — | $0 (rejected) | None accepted | N |
Each line connects back to source documents such as the TTM P&L, tax returns, general ledger detail, owner payroll records, the related-party lease and an independent rent opinion, invoices for one-time items, and a short written rationale memo.
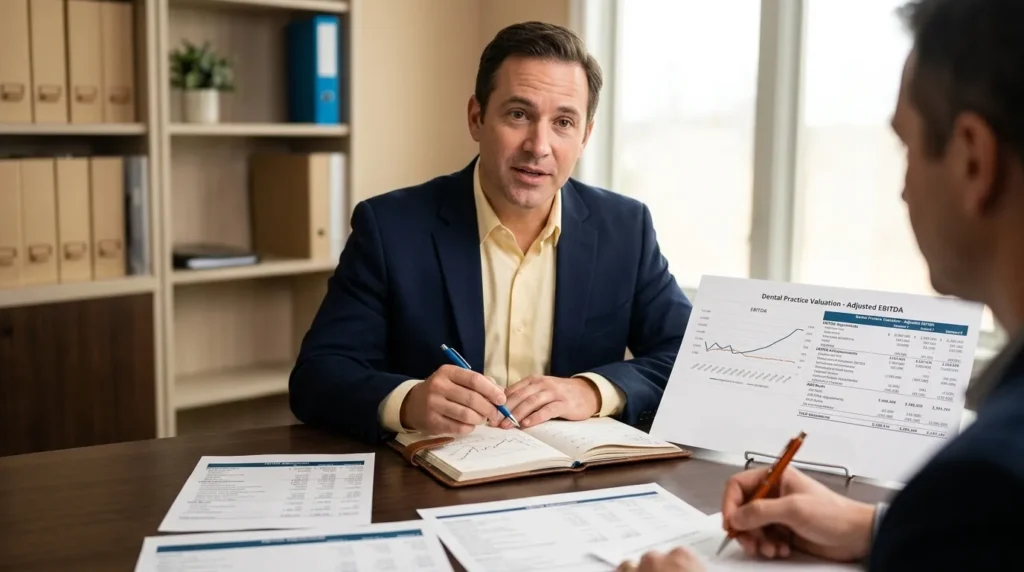
The decisive concept is three EBITDA figures: reported, seller-adjusted, and buyer-adjusted. The gap between the last two can be where price is won or lost in QoE review.
In the worked example, the buyer’s QoE team rejects the recurring marketing add-back and increases the replacement cost based on production data.
- Seller-adjusted EBITDA: reported EBITDA plus legitimate add-backs minus deductions
- Buyer strikes marketing add-back: EBITDA decreases by the disallowed amount
- Buyer increases replacement cost: EBITDA decreases further
- Buyer-adjusted EBITDA: seller-adjusted EBITDA less the buyer’s disallowed add-backs and additional deductions
Every dollar of that gap is multiplied by the deal multiple. At a hypothetical 7x multiple, each $1 of EBITDA disagreement represents $7 in price, before any change to the multiple itself.
Buyers commonly reject add-backs such as a family member who actually performs necessary work, marketing the seller says could be cut, a “one-time” expense appearing in three consecutive years, deferred maintenance framed as efficiency, and savings from understaffing. The pattern is that expenses which continue under new ownership, or which lack documentation, usually remain in the P&L.
From Adjusted EBITDA to an Implied Value Range
Buyer-adjusted EBITDA becomes the base that supports an implied enterprise value range once a multiple is applied. Several factors can move the applicable multiple. Practice size and EBITDA level can matter most, followed by the number of providers and how dependent the practice is on the owner.
Revenue durability, such as hygiene share, recall rates, and active patient count, can also influence the multiple. Payer mix, specialty, geography, and the quality of the financial records themselves can play a role as well. For a detailed discussion of how multiples are determined, see How Are Dental Practice Valuation Multiples Calculated? and Dental Practice EBITDA Valuation: Multiples & Key Factors.
The SDE-versus-EBITDA distinction matters here. A private-buyer SDE multiple and a DSO EBITDA multiple apply to different earnings bases and cannot be compared directly.
The worked example above can also support an illustrative DSO multiple range. Suppose buyer-adjusted EBITDA settles at $1,300,000 after QoE review.
- Buyer-adjusted EBITDA: $1,300,000 after the buyer’s disallowed add-backs and additional deductions
- Illustrative multiple range of 6.5x to 7.5x: implies an enterprise value range of $8,450,000 to $9,750,000 before debt, working capital, real estate, and transaction costs
- Every dollar of EBITDA difference between seller-adjusted and buyer-adjusted flows through that entire value range
These figures are illustrative. The actual value a practice commands can depend on the specific buyer pool, competitive process, and diligence outcome.
Why a CPA-Led Schedule Protects Price
McLerran & Associates builds a CPA-led, diligence-grade EBITDA analysis up front, unpacking every add-back, documenting every line, and preparing the schedule before the deal goes to market. This approach helps the number hold when a buyer’s QoE team reviews it and can reduce the risk of a re-trade.
The firm’s track record reflects this approach: more than 10,000 dental practices evaluated, approximately 2,000 successful sales, roughly $2 billion in closed transaction volume, and a transaction rate of approximately 85–90%, compared with an industry norm closer to 35–40%. McLerran & Associates works exclusively on the sell side and runs both the private-buyer and DSO transaction paths in roughly equal measure, which gives owners a genuine side-by-side comparison.
A DIY seller usually has no EBITDA analysis at all. A local generalist broker may produce one, but often not at diligence grade. Multi-vertical advisors and free-valuation lead-generation firms frequently stop at the estimate, which can leave no one to defend the number when a buyer’s team pushes back.
Conclusion
The adjustment schedule is the document that can determine price. An unsupported EBITDA number functions as a wish. A documented schedule, with direction, dollar amount, and supporting evidence for every line, functions as a price that has a better chance to hold. Building dental practice valuation adjustments for EBITDA carefully, before the deal goes to market, can separate a number that survives diligence from one that gets re-traded.
McLerran & Associates builds that schedule. To discuss your practice, your goals, and what your number could look like with a CPA-led analysis behind it, schedule a free, confidential discovery call: call (512) 900-7989 or email info@dentaltransitions.com, or use the button below. Owners not yet ready to sell may also consider the McLerran M&A Summit (October 29–30, 2026), a dental-only event that awards 4 CE credits and includes a complimentary practice valuation.
Frequently Asked Questions
What Is the Formula for Calculating Adjusted EBITDA for a Dental Practice?
Adjusted EBITDA equals reported EBITDA plus legitimate add-backs minus deductions. Add-backs typically include the owner’s recorded compensation and personal or discretionary expenses. They also cover excess family payroll, above-market related-party rent, and documented one-time costs. Deductions include the market-rate cost of replacing the owner’s clinical and management work and any below-market related-party rent that understates what a buyer will actually pay. The result should reconcile to tax returns and be supported by a document for every line.
Is It Better to Use EBITDA or Adjusted EBITDA?
Reported EBITDA in an owner-operated dental practice is rarely the right number to price a deal. Tax returns are often structured to minimize taxable income, which depresses reported earnings. Adjusted EBITDA, restated to reflect what a new owner would likely earn with owner-specific costs removed and non-arm’s-length arrangements corrected, is the figure institutional buyers and DSOs commonly use to price a practice. For doctor-to-doctor sales, seller’s discretionary earnings (SDE) is often more relevant because it retains the owner’s full compensation for a buyer who will personally work in the practice. The right metric can depend on the buyer type and transaction path.
What Is the 30% EBITDA Rule?
In dental practice valuation, the “30%” figure most commonly refers to the approximate market rate used to replace an owner-dentist’s clinical production, typically cited as roughly 28–35% of the owner’s adjusted production, depending on specialty, geography, and the specific role. This replacement cost is deducted from the owner’s add-back to arrive at adjusted EBITDA. It functions as a guideline rather than a universal rule, and the appropriate rate should be benchmarked against state and specialty data rather than applied mechanically. A separate benchmark sometimes referenced is that a well-run general dental practice may produce adjusted EBITDA in the range of roughly 15–25% of collections, with solo owner-operator practices typically at the lower end (about 15–18%) and multi-provider practices higher. Actual margins can vary based on overhead structure, payer mix, and staffing model.
How Do You Normalize Owner Compensation and Related-Party Rent?
Owner compensation normalization starts by adding back all recorded owner pay, including salary, draws, retirement contributions, and personal benefits. The next step subtracts the market cost of replacing the owner’s clinical and management work. Clinical replacement cost is typically benchmarked as a percentage of the owner’s production, with the specific rate depending on specialty and geography. If the owner was paid above market, the net adjustment can increase EBITDA. If the owner was paid below market, it can reduce EBITDA.
Related-party rent is normalized by comparing the recorded rent to an independent fair-market-rent opinion. If the practice pays below-market rent to an owner-controlled entity, the shortfall is deducted from EBITDA because the buyer will sign a market-rate lease. If the practice pays above-market rent, only the excess over market is added back. Both adjustments usually require an independent rent appraisal or opinion to survive diligence, because the owner’s own estimate rarely serves as sufficient evidence.
How Many Times EBITDA Is a Dental Practice Worth?
There is no fixed answer. The applicable multiple can depend on several factors, including the size and level of adjusted EBITDA, the number of providers, and the degree of owner dependence. Revenue durability, such as hygiene share, recall rates, and active patient count, can also influence the multiple. Payer mix, specialty, geography, and the quality of the financial records can matter as well.
Private buyer (doctor-to-doctor) deals are typically priced on SDE rather than EBITDA, and the two multiples are not directly comparable because they apply to different earnings bases. DSO and private equity buyers usually price on adjusted EBITDA, with the multiple often rising as EBITDA scale increases and owner dependence decreases. Specialty can also influence the range, because some specialties attract stronger buyer demand than others. The practical answer is that the multiple a specific practice commands is determined by its numbers, buyer pool, and competitive process, which is what a diligence-grade valuation aims to quantify.
Which Add-Backs Get Rejected in Diligence?
The body section above lists the add-backs buyers reject most often. The pattern behind them is consistent: when an expense will continue under new ownership, or when the seller cannot document it, buyers usually keep it in the P&L. Every rejected add-back is multiplied by the deal multiple, so a weak or unsupported schedule can have an outsized impact on price.